

Upflow → Blog → AR metrics
Reducing Balance Method of Depreciation: Formula & Guide
Aashima Lamba
|
1 August 2025
Generate AI summary


When your business invests in tech infrastructure, delivery vehicles, or high-performance laptops, those assets don’t hold their value forever. Depreciation helps you reflect that decline in financial terms. But here’s the catch, not all depreciation methods tell the same story.
For fast-moving businesses, especially those in SaaS, logistics, or capital-intensive industries, the reducing balance method offers a more accurate, tax-efficient way to record asset value over time. And for UK businesses, it’s particularly important to understand how this method affects your financial statements and corporation tax planning. Keep reading to know about:
- What Is the Reducing Balance Method of Depreciation?
- Reducing Balance Depreciation Formula
- Reducing Balance Depreciation Calculation Example
- Industry Use Cases
- Tax Implications in the UK
- Advantages of the Reducing Balance Method
- Disadvantages of the Reducing Balance Method

What Is the Reducing Balance Method?
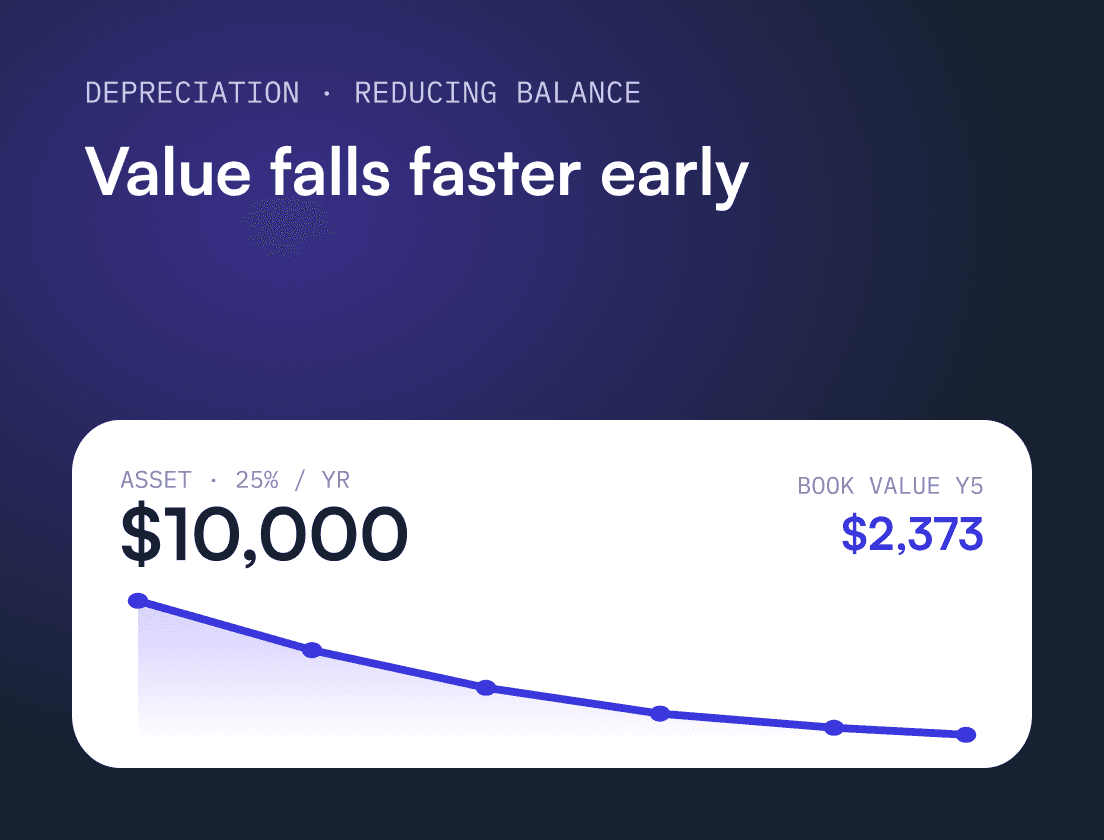
The reducing balance method of depreciation applies a fixed percentage to the net book value of an asset each year, rather than to its original cost. This results in higher depreciation charges in the early years, tapering off over time.
It’s ideal for assets that:
- Lose value quickly (e.g. servers, delivery vans, or specialist equipment)
- Generate more value in the early part of their lifecycle
- Face high maintenance or obsolescence costs in later years
Example:
- Asset cost: £10,000
- Depreciation rate: 25%
Year 1: £10,000 × 25% = £2,500
Year 2: £7,500 × 25% = £1,875
…and so on.
Why Businesses Are Turning to Reducing Balance Depreciation
According to HMRC guidance, companies can use any reasonable depreciation method in their accounting books, even if it differs from the approach used for tax capital allowances.
But here’s why companies (particularly fast-growing SMEs) favour the reducing balance method:
- Cash Flow Planning: Higher initial depreciation can reduce reported profits, often aligning with lower tax obligations early on.
- More Accurate Valuation: Matches the real-world value loss of tech, vehicles, or equipment.
- Investor Transparency: Helps investors understand your financial performance based on asset productivity, not just amortisation schedules.
Reducing Balance Depreciation Formula
Depreciation Expense = Net Book Value × Depreciation Rate
Where:
- Net Book Value = Asset Cost - Accumulated Depreciation
- Depreciation Rate is typically between 20% and 40% depending on the asset class and its useful life.
💡 If you’re using residual value for more accuracy:

Depreciation = (Net Book Value − Residual Value) × Depreciation Rate
How to Calculate It (Step-by-Step)
Let’s say you purchase a developer workstation for £5,000 with a 30% depreciation rate.
| Year | Net Book Value | Depreciation | Closing Value |
|---|---|---|---|
| 1 | £5,000 | £1,500 | £3,000 |
| 2 | £3,500 | £1,050 | £2,450 |
| 3 | £2,450 | £735 | £1,715 |
| 4 | £1,715 | £514.50 | £1,200.50 |
Unlike straight-line, the amount depreciated decreases every year, just like the usefulness or resale value of the asset.
Industry Use Cases
1. SaaS & Tech Startups
SaaS firms often invest in expensive hardware: servers, MacBooks, routers – that lose value quickly. The reducing balance method mirrors this drop-off and aligns costs with real asset usage.
2. Logistics Companies
Fleet vehicles depreciate faster in the early years due to mileage and wear. Using reducing balance better reflects this reality on the balance sheet.
3. Creative Agencies
Design firms using high-end workstations or render engines can depreciate more upfront and align with fast-moving tech cycles.
4. Manufacturing & R&D
Capital-intensive machinery often becomes obsolete due to automation or tech upgrades, especially in sectors like pharmaceuticals or clean tech.
Tax Implications in the UK
Although depreciation isn’t tax-deductible for UK corporation tax, it impacts your accounting profits, which can influence your capital allowance strategy and financial planning.
Key Points:
- For tax, you'll usually claim capital allowances (like the Annual Investment Allowance - AIA).
- However, the depreciation method used in your accounts can impact deferred tax liabilities and investor relations.
- Many firms pair reducing balance depreciation in accounting with flat-rate tax allowances for compliance.
Speak to your accountant to align your book depreciation with HMRC’s capital allowances in a way that supports both reporting accuracy and tax efficiency.
Advantages of the Reducing Balance Method
1. More Accurate Asset Valuation:
This method allocates higher depreciation expenses during the earlier years of an asset’s life when its productivity and market value are highest. This is especially useful when assets decline rapidly in value or productivity.
Why it matters:
For fast-depreciating assets like vehicles, machinery, or IT equipment, the reducing balance method gives a more realistic book value on your balance sheet particularly useful for audits, financing, or asset-backed lending.
2. Better Matching of Revenue & Cost:
The reducing balance method aligns with the matching principle in accounting by recognizing higher depreciation when the asset delivers the most value. It improves the matching principle by aligning depreciation with an asset’s usefulness.
What this means for you:
It ensures that the expense of using the asset is recorded in the same periods as the revenue it helps generate, ideal for businesses with seasonality or high upfront productivity.
3. Favourable Early-Year Tax Positioning:
By accelerating depreciation, businesses report lower net profits in the initial years of asset use which can aid cash flow.
Benefit:
This can lead to reduced taxable income and improved early-stage cash flow, which is critical for startups or capital-intensive businesses.
4. Supports Strategic Asset Replacement:
As depreciation tapers off, the declining expense signals when an asset may be approaching obsolescence or underperformance.
Why this helps:
It empowers finance teams to build data-backed asset replacement strategies, improving operational efficiency and budget planning.
Disadvantages of the Reducing Balance Method
1. Complexity:
Each year requires recalculating depreciation based on the remaining book value rather than the original cost.
However:
Most cloud accounting platforms (like Netsuite, Xero, QuickBooks – all Upflow integrations) automate this process, making it manageable for finance teams of all sizes.
2. Non-Zero Residual Value:
The asset never fully depreciates on paper using this method, potentially creating discrepancies in long-term reporting.
What to consider:
Accountants often apply a manual adjustment or switch to the straight-line method in later years to ensure full depreciation.
3. Inconsistent Yearly Charges:
Annual depreciation amounts decrease over time, which can lead to forecasting challenges.
4. Impact on budgeting:
For businesses relying on fixed costs for future projections, this variability can complicate expense planning and distort KPIs.
In a financial world where agility, accuracy, and strategic forecasting are more important than ever, the reducing balance method gives modern businesses a smart, transparent way to reflect the true value of their assets.
Whether you’re managing developer machines, warehouse equipment, or commercial vehicles, this method aligns with how your tools perform, not just how long they’re expected to last.
Bring more accuracy and strategy to your financial operations. Book a demo with Upflow and discover how real-time AR insights can help you optimise cash flow and plan smarter for growth.

Aashima Lamba
Marketing Director at Upflow
About the Author
Aashima Lamba is the Marketing Director at Upflow, where she leads the company’s global growth initiatives across digital, content, and campaign strategy. With a deep understanding of the SaaS buyer journey and full-funnel marketing, Aashima builds programs that attract, engage, and convert high-intent finance audiences.
At Upflow, she works closely with sales, product, and customer teams to ensure messaging resonates across every touchpoint, from thought leadership to revenue-driving campaigns. Her approach blends data-driven decision-making with creative storytelling to fuel brand awareness, pipeline generation, and customer retention.
With her deep understanding of finance audiences and unique perspective from collaborating across marketing, product, and sales, Aashima creates content that speaks directly to the challenges and goals of modern revenue teams. Her contributions to the Upflow blog turn industry insights into actionable messaging that resonates with finance leaders.

Summary

Shared
FAQs
Can’t find what you’re looking for?
Ask AI
The straight-line method spreads depreciation evenly over an asset’s useful life, with the same amount charged each year. It’s ideal for assets that provide consistent value over time, like office furniture or long-term software licenses.
The reducing balance method applies a fixed percentage to the asset’s declining book value each year, leading to larger depreciation charges early on and smaller ones later. It’s better suited for assets that lose value quickly, such as tech equipment, vehicles, or machinery.
Double-declining applies twice the straight-line rate aggressive, useful for assets with extreme early usage. It’s a form of reducing balance, but more intense.
Depreciation doesn’t reduce your corporation tax bill directly, as it’s not tax-deductible in the UK. However, it affects your accounting profits, which can influence your financial reporting, forecasting, and investor relations.
For tax purposes, businesses claim capital allowances such as the Annual Investment Allowance (AIA), instead of accounting depreciation.
No problem, you can subtract it from the book value in the depreciation formula to prevent over-depreciation.
Related articles