The cash application process is how every customer payment gets matched to the right invoices before it counts in your books. For most B2B finance teams, it’s still one of the most manual parts of accounts receivable, with bank feeds in one place, remittance emails in another and a spreadsheet holding it all together.
The work grows with every new customer. More customers means more payments, more remittance formats, more short payments to chase and more cash sitting unapplied while the invoices it covers still look overdue.
Automation can take over most of that matching, so your team only deals with the payments that need a person. In this guide, you’ll learn:
Cash application is the accounts receivable step where incoming customer payments are matched to the invoices they pay and posted to your ERP. It’s the point where “we sent an invoice” becomes “we’ve been paid”. When remittance details are missing or a customer pays several invoices at once, it’s also where AR time disappears and unapplied cash starts to build up.
Cash application comes near the end of the accounts receivable process and your wider order-to-cash (O2C) cycle. By then you’ve delivered the product or service, sent the invoice and followed up, and the payment has arrived.
Until that payment is applied, your systems still treat the invoice as unpaid, and the effects reach well beyond AR:
Customers who have already paid can get reminders, which strains the relationship.
DSO looks higher than it really is.
Cash forecasts and aging reports run on outdated numbers.
Month-end close takes longer, because the books don’t match the bank balance.
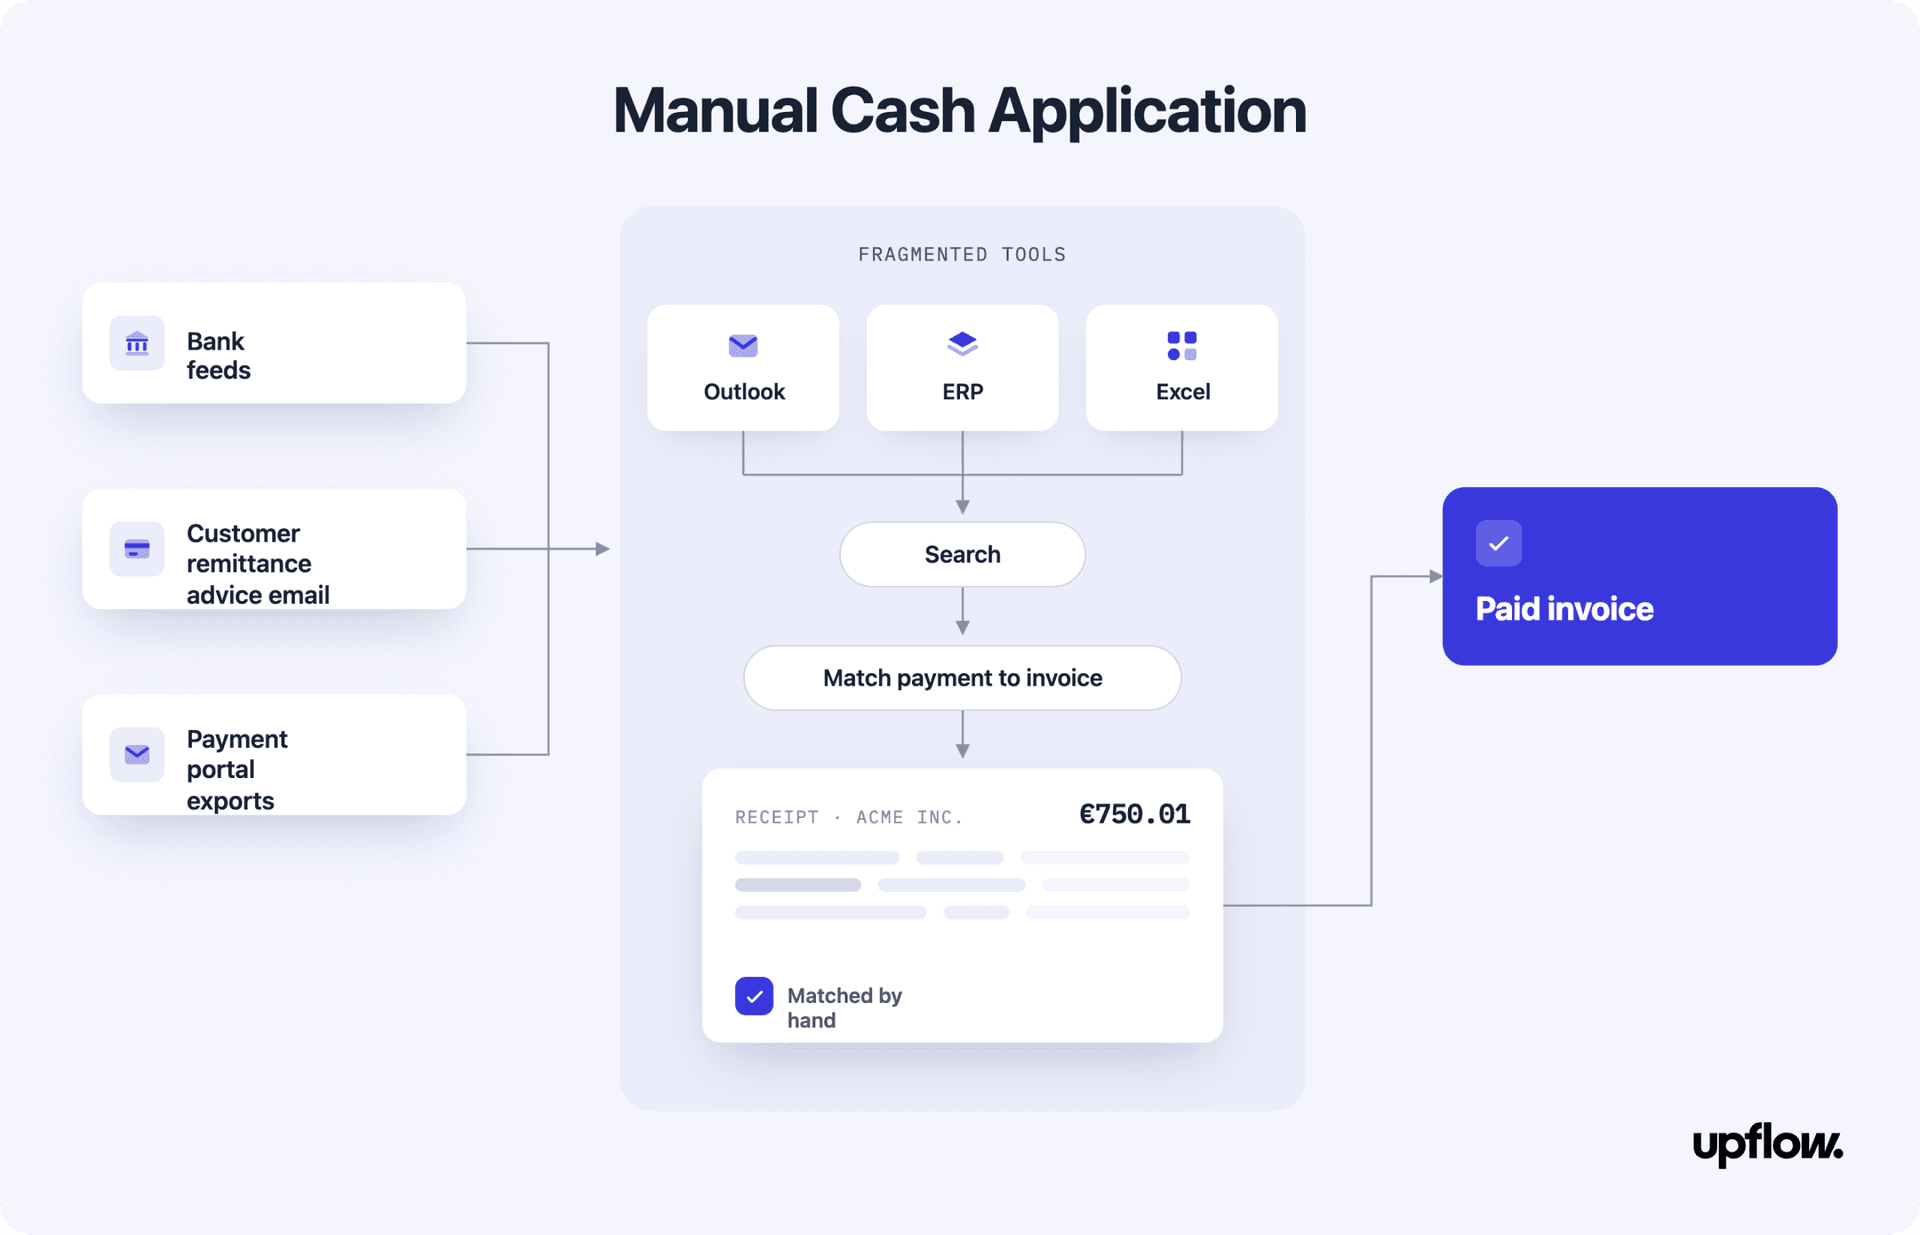
Many finance teams still apply cash by hand. Payment and remittance details arrive from different places, and someone has to pull them together from:
Then they reconcile each payment against open invoices, one at a time. Every source has its own format, so even a single day’s batch can take hours to piece together, and each manual step is another chance for a mismatch.
What are the steps in the cash application process?
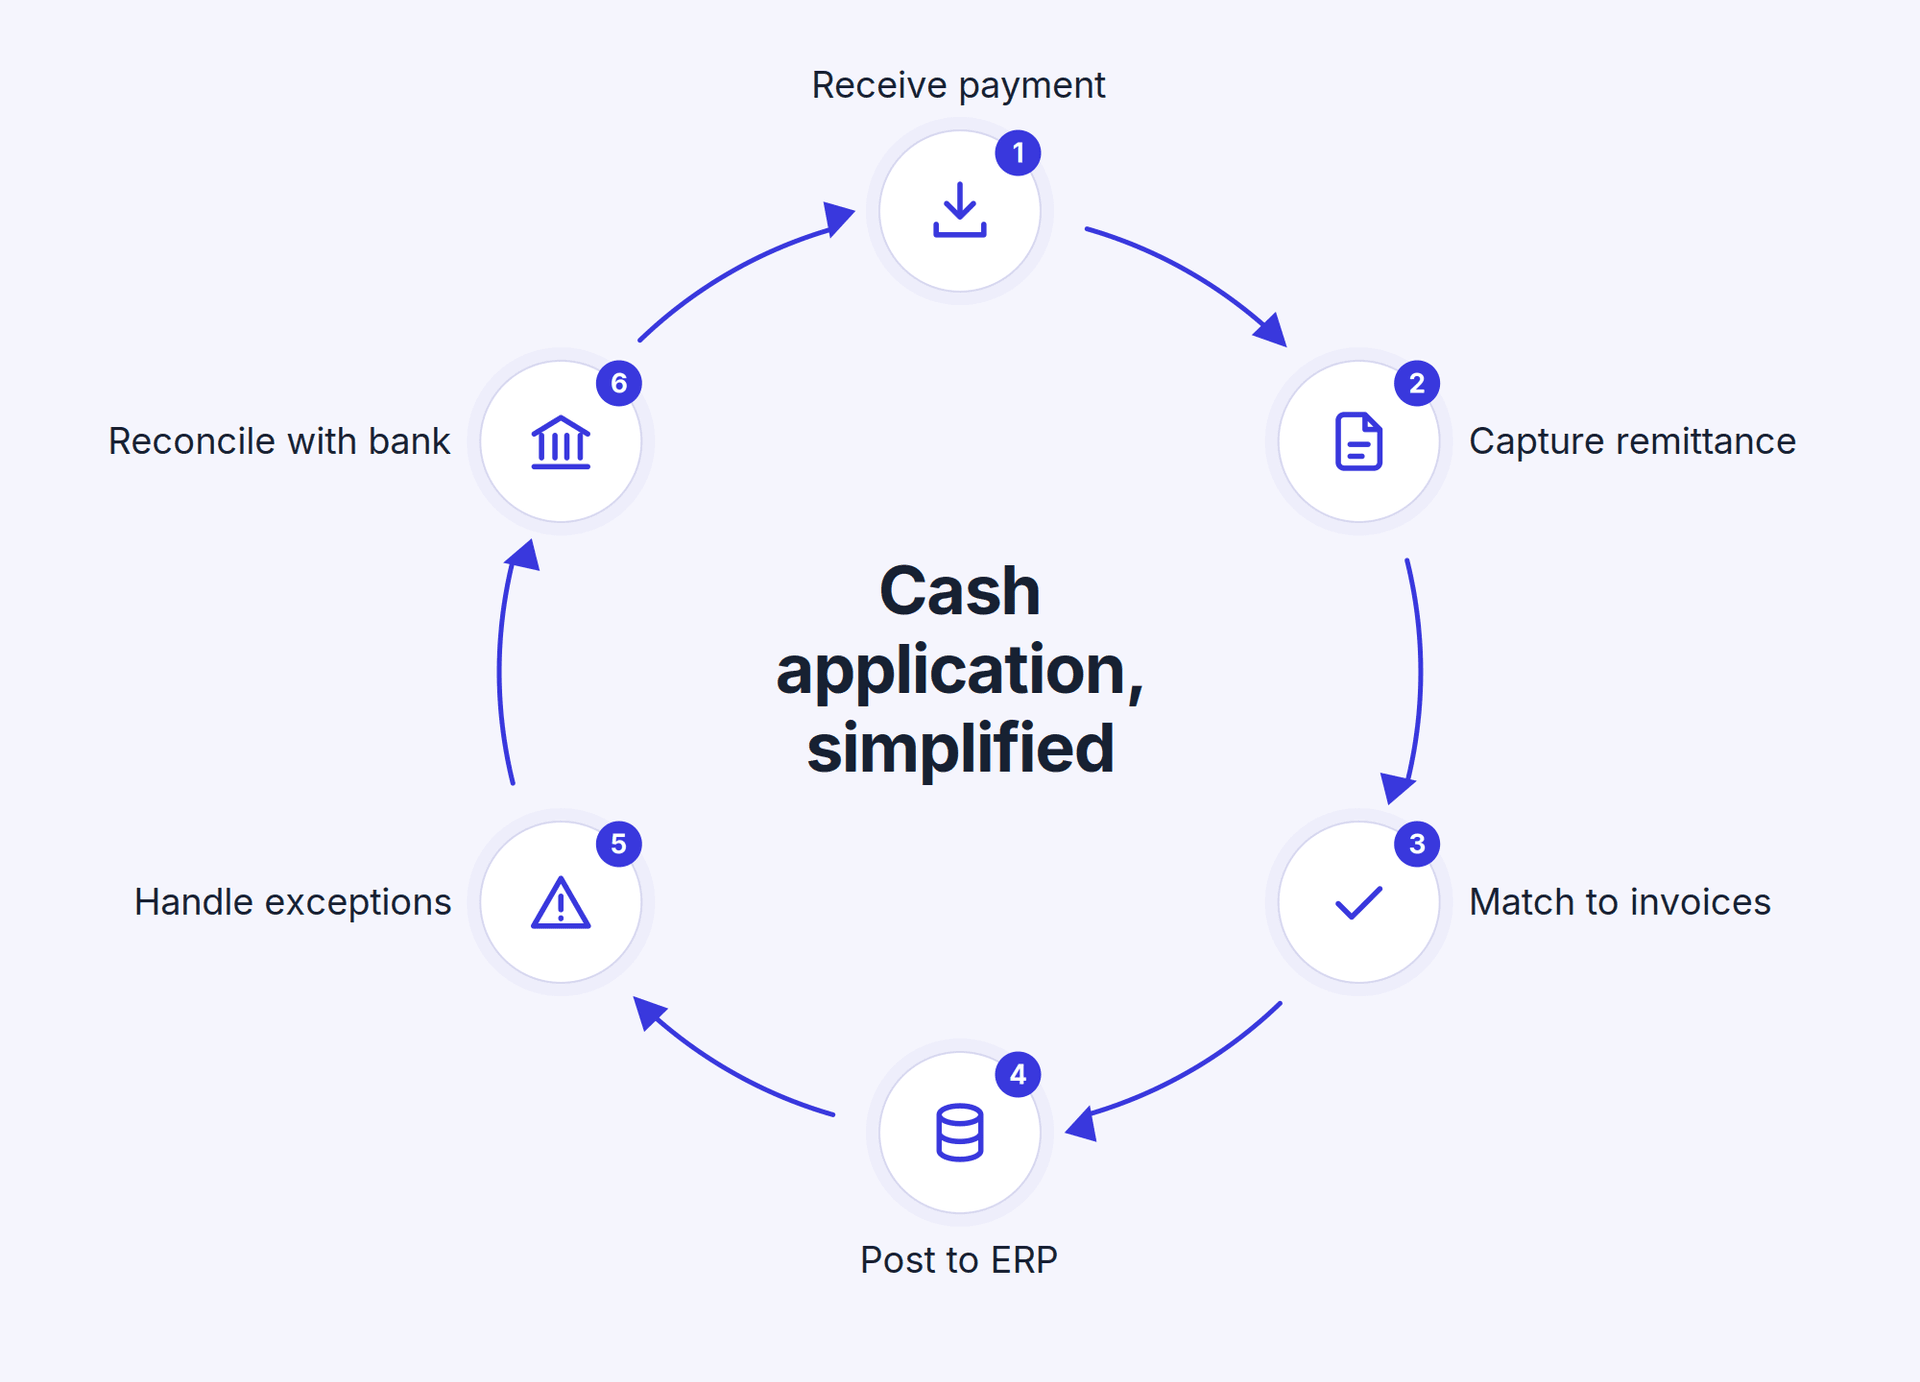
The cash application process has six steps: receive the payment, capture the remittance details, match the payment to invoices, post the matched payments to the ERP, handle exceptions, and reconcile against the bank. The data for each step rarely arrives in one place, which is why each one takes longer than it should when done by hand.
Receive the payment. Payments come in through bank feeds, lockbox deposits, card processors and payment portals. Customers pay with different payment methods, and each one shows up in the bank with a different level of detail.
Capture the remittance details. The remittance advice tells you which invoices a payment covers. It might arrive as an email, a PDF, a portal download or a line of text in the bank reference, and it often arrives days after the payment itself.
Match the payment to invoices. Each payment is matched to outstanding invoices using invoice numbers, amounts, customer names or reference numbers. A single payment for a single invoice is quick. A payment covering several invoices, or one that doesn’t match any open amount, takes real investigation.
Post matched payments to the ERP. Clean matches are posted to your accounting system straight away, which marks invoices as paid and updates customer balances. Your aging report and collections workflows then reflect what has actually been paid.
Handle exceptions. Short payments, overpayments, payments with no remittance and payments from an unknown payer go into an exception queue. Someone on the team works out what the customer meant to pay, applies it, and posts it once resolved.
Reconcile against the bank. Finally, the cash posted in the ERP is checked against the bank statement, so the books and the bank balance agree before month-end close.
Where does remittance information come from?
Remittance information comes from five main places: lockbox files, bank payment references, remittance emails and PDFs, customer AP portals, and EDI files. Each one arrives in a different format and on a different schedule, and the gaps between them are where most matching delays start.
The payment and the remittance usually travel separately. An ACH payment can land in your bank with a short, truncated reference, while the details of which invoices it covers arrive by email two days later. Until both are in hand, the payment can’t be applied with confidence.
Remittance source
Typical format
What usually goes wrong
How to fix it
Lockbox files
Bank-generated data file with scanned check stubs
Stubs missing or illegible, invoice numbers left off
Ask your bank for image capture and data extraction, and print invoice numbers on your remittance slips
Bank payment references
A text field on the ACH or wire transfer
Reference cut off by character limits, or filled with the customer's own internal ID
Ask customers to put your invoice number first in the reference field
Remittance emails and PDFs
Free-form email or attached PDF from the customer's AP team
Arrives late, sent to the wrong inbox, or covers dozens of invoices in one document
Use one dedicated remittance address and capture data from attachments automatically
Customer AP portals
Remittance details stored in the customer's supplier portal
Someone has to log in and download them, portal by portal
Keep a list of portal logins by customer and set a regular check, or use tools that pull the data in
EDI files
Structured EDI 820 payment order and remittance advice
Mapping errors between the customer's codes and your invoice numbers
Validate the mapping when onboarding each EDI customer
The most reliable fix is to collect remittance information at the point of payment. When customers pay through a white-label payment portal, they select the invoices they’re paying, so the remittance data comes with the payment and no separate document is needed. A standard remittance template, printed on every invoice, helps with the customers who still pay by bank transfer.
How do you handle short payments, overpayments and unapplied cash?
Apply short payments to the invoices they were meant for and keep the remaining balance open with a reason. Record overpayments as a customer credit. Investigate unapplied cash quickly, so it doesn’t sit in a suspense account while the customer keeps getting reminders. Clear rules for each case let your team resolve exceptions the same way every time.
Short payments happen when a customer pays less than the invoice total. Common causes are bank fees, a discount the customer took, or a disputed line item.
Overpayments happen when a customer pays more than they owe, often by paying an invoice twice or paying ahead of the next invoice.
Unapplied cash is money that has reached your bank account but can’t yet be matched to an invoice, usually because the payer or the invoices covered can’t be identified. Until it is applied, it shows up in your books as unapplied credits, and the related invoices still look unpaid.
A worked example
Acme Inc. has three open invoices: INV-1041 for $12,000, INV-1042 for $8,500 and INV-1043 for $4,200. Over one week, three payments arrive:
Payment
What arrived
What happened
How to apply it
Short payment
$20,000, remittance lists INV-1041 and INV-1042
The two invoices total $20,500, so the customer paid $500 less
Apply $12,000 to INV-1041 and $8,000 to INV-1042. Leave $500 open on INV-1042 with a reason code and follow up
Overpayment
$4,700, remittance lists INV-1043
The invoice is $4,200, so the customer paid $500 more
Close INV-1043 and record $500 as a customer credit, to apply to the next invoice or refund
Unapplied cash
$24,700 from "ACME HOLDINGS LLC", no reference
The payer name doesn't match the customer record and no invoices are listed
Hold it as unapplied cash, contact the customer's AP team, and apply it once confirmed
The third payment is the one that causes the most trouble. Acme has paid in full, but until someone links the payment to the account, all three invoices still look open. Automated payment reminders can go out to a customer who has already paid, which is an easy way to damage a good relationship.
Rules worth setting before exceptions pile up
A tolerance threshold. Small differences, such as a bank fee under a set amount, can be written off automatically instead of being chased.
Reason codes. Tag every short payment with a cause, such as fee, discount, dispute or error, so you can spot patterns by customer.
An owner for each exception. Unmatched payments should land with a named person, not a shared inbox.
An age limit for unapplied cash. Anything unapplied after a few days should be escalated, and the balance should be cleared before month-end close.
Why is manual cash application hard to scale?
Manual cash application grows with your payment volume, not with your team. Every new customer adds another remittance format, another payer name to recognize and more exceptions to work through. Past a certain volume, the only way to keep up is to hire. A NACM poll found that 55% of companies already dedicate one or two AR team members to cash application.
Four problems make it hard to scale:
Data is scattered across tools. Payments arrive through bank feeds, while remittance details sit in email threads, PDFs and customer portals. None of these sources connect to each other, so someone has to piece them together by hand.
Matching relies on manual searches. Teams search spreadsheets, inboxes and the ERP for a matching amount, customer name or invoice number. Each search takes a few minutes, and on a busy day those minutes become hours.
The books lag behind the bank. Even after payments are matched, posting to the ERP often happens in batches. Until then, your AR balance and cash forecast run on yesterday’s numbers.
Small errors spread. One misapplied payment or missing remittance note can leave an invoice looking overdue, inflate DSO and send reminders to customers who have already paid.
The cost adds up quickly. As an illustration, one person spending two hours a day on cash application works out to about 480 hours a year. At a loaded cost of $50 an hour, that’s roughly $24,000 a year in time alone, before counting the cost of payments applied late or to the wrong invoice.
Manual cash application
Automated cash application
Time spent
Hours each day, growing with payment volume
Team time goes to reviewing exceptions only
Matching accuracy
Depends on who does the matching and how busy they are
Consistent rules and AI matching, with every match logged
Exception handling
Handled differently by each team member
Routed to a named owner with a clear reason
Reporting
AR balances and aging lag behind the bank
Balances update as soon as payments are posted
Growth
More customers means more headcount
Volume grows without adding people at the same rate
DSO impact
Inflated by payments received but not yet applied
Reflects what customers have actually paid
Team focus
Repetitive searching and matching
Exceptions, disputes and customer follow-up
How does cash application automation work?
Cash application automation captures payment and remittance data in one place, matches payments to invoices with a mix of rules and AI, sends anything it can’t match to an exception queue, and posts the results back to your ERP. Your team stops matching every payment by hand and spends its time only on the payments that need a decision.
Rules-based matching handles the predictable cases. If the amount, customer and invoice number line up, the payment is applied. Rules like these, the same logic behind RPA in accounting, work well when customers pay one invoice at a time and include the right reference.
AI matching handles the rest. It reads remittance emails and PDFs, recognizes payer names that don’t match the customer record, and splits a single payment across several invoices. It also learns from how each customer usually pays, so a customer who always leaves off the invoice number or pays in batches gets matched correctly over time.
The exception queue is where the remaining payments go: short payments, overpayments, unknown payers and anything below a confidence threshold. Each exception arrives with a suggested match and a reason, so the reviewer confirms or corrects it instead of starting from scratch.
ERP sync closes the loop. Matched payments are written back to your accounting system automatically, so invoices are marked as paid, balances update and collections stop chasing customers who have already paid. Each ERP handles this differently. For a closer look at one setup, the guide to automated cash application in NetSuite covers where native matching stops and what fills the gap.
Where Upflow fits
Upflow Cash App captures remittance details from emails, PDFs and lockbox files, matches payments with AI that adapts to each customer’s payment patterns, and leaves only the exceptions for your team to review. Results post back to your ERP automatically. If you’re comparing options, the main tools differ most on matching approach and ERP coverage, as this roundup of the best cash application software shows.
Which cash application KPIs should you track?
Track four KPIs: auto-match rate, unapplied cash as a share of receipts, time to apply, and exceptions per 100 payments. Together they show how much of the work is automated, how much cash is stuck, and where the process slows down. Review them weekly alongside your wider accounts receivable KPIs.
KPI
What it measures
How to calculate it
What to look for
Auto-match rate
How many payments are applied without anyone touching them
Payments matched and posted automatically ÷ total payments received × 100
A steady rise as rules and AI learn your customers' habits
Unapplied cash ratio
How much received cash is still waiting to be applied
Unapplied cash balance ÷ total cash received in the period × 100
A low, stable figure, and close to zero at month-end
Time to apply
How long payments take to reach the ERP after hitting the bank
Average time from bank receipt to ERP posting
Same-day posting for clean matches
Exceptions per 100 payments
How often payments need manual review
Exceptions ÷ total payments received × 100
A falling trend, with recurring causes traced back to specific customers
These KPIs also explain movements in your headline metrics. If days sales outstanding jumps while collections look healthy, a rising unapplied cash ratio is often the reason, since customers have paid but the payments haven’t been applied. Tracking all four on an AR dashboard makes those patterns easy to spot.
What are cash application best practices?
The best cash application practices make the work predictable. Get remittance details at the point of payment, standardize how they reach you, set clear rules for exceptions, post every day and measure the results weekly. Most of these changes work with any system, before you automate anything.
Capture remittance at the point of payment. When customers pay through a portal or an online payment system that lets them select the invoices they’re paying, the remittance data arrives with the payment and there’s nothing left to match by hand.
Use one remittance inbox and one template. Send all remittance advice to a single shared address, and print a short remittance template on every invoice. Customers who pay by bank transfer then know exactly what to include.
Ask for the invoice number in the payment reference. Bank reference fields are short, so ask customers to put your invoice number first. It’s the single most useful piece of information for matching.
Write down how exceptions are handled. A one-page SOP covering tolerance thresholds, reason codes, who owns each type of exception and when to escalate keeps the process consistent when people are out or the team grows.
Post matched payments every day. Batching postings to the end of the week keeps AR balances out of date and leads to reminders being sent to customers who have already paid.
Bring in sales and customer success on tricky exceptions. When a payer can’t be identified or a short payment looks like a dispute, the account owner often knows the answer straight away.
Audit a sample of matches each month. Check a handful of applied payments against the remittance to catch misapplications early, and review your accounts receivable tracking for invoices that should have closed but haven’t.
Your 30-day cash application roadmap
Week 1: Measure your starting point
Record how many hours the team spends on cash application each week.
Tell customers how to reference invoice numbers in their payments.
Week 3: Define exception handling
Agree on tolerance thresholds and reason codes.
Assign an owner to each exception type.
Write the exception SOP.
Week 4: Get visibility and review
Track the four KPIs above for the first time.
Get real-time AR visibility with Upflow’s Discover Plan, which is free.
Decide which parts of the process to automate first.
Cash application rarely gets much attention, but every other part of AR relies on it being right. Want to see where your process stands today? Book a call with our team.
Côme is the Director of Financial Services at Upflow, where he leads the development of cutting-edge solutions at the intersection of technology, finance, and customer experience. He plays a key role in shaping the vision and execution of Payments by Upflow, Upflow’s next-generation B2B payment platform.
At Upflow, Côme focuses on delivering frictionless, secure, and intuitive payment experiences that bring the best of B2C e-commerce to B2B transactions. From modern payment infrastructure to AR financing, his work helps finance teams streamline collections, enhance customer satisfaction, and unlock greater cash flow efficiency.
Known for his insights into fintech innovation, payment optimization, and regulatory navigation, Côme is a regular contributor to Upflow’s blog. He shares expert perspectives on how finance teams can use modern tools to enhance cash flow, improve customer experiences, and future-proof their payment operations.
Cash application is the accounts receivable step where incoming customer payments are matched to the invoices they pay and posted to your ERP. It confirms which invoices are paid, keeps customer balances accurate, and makes sure your AR reports and collections work from real payment data.
Cash application matches each customer payment to the invoices it covers. Bank reconciliation checks that the total cash recorded in your books agrees with your bank statement. Cash application happens first and works payment by payment. Reconciliation comes after and confirms the overall balances line up, usually before month-end close.
Payment processing is how money moves from the customer to you, through card, ACH, wire or another method. Cash application happens once that money arrives. It matches the payment to the right invoices in your accounting system and updates the customer’s balance.
Unapplied cash is money that has reached your bank account but hasn’t been matched to an invoice yet. It usually happens when the payer can’t be identified or the remittance details are missing. Until it’s applied, the related invoices still look unpaid, which can trigger reminders to customers who have already paid.
A partial payment has to be split across the right invoices, and the remaining balance kept open with a reason. Without clear remittance details, someone has to work out what the customer meant to pay before it can be applied.
It goes into an exception queue as unapplied cash. Someone on the team identifies the payer and the invoices it covers, often by contacting the customer, then applies and posts it.
It depends mostly on the quality of the remittance data. Payments with a clear invoice reference match reliably with simple rules. AI matching handles messier cases, like missing references or one payment covering several invoices, and gets more accurate as it learns each customer’s habits. Your auto-match rate is the best way to measure it over time.
Most of it can. Payment capture, remittance extraction, matching and ERP posting can all run without anyone touching them. A small share of payments will always need a person, such as unknown payers, disputed short payments or unusual overpayments. The goal is to make that review quick and consistent.