

Upflow → Blog → AR metrics
Average Collection Period: Formula, Calculation & Examples
Alexandre Antoine
|
October 23, 2026
Generate AI summary


Average collection period is a key financial metric that shows how long it takes for your business to collect payments from customers after a credit sale. It’s calculated by dividing your average accounts receivable by your net credit sales, then multiplying by the number of days in the period. The result gives you a clear, time-based view of how efficiently your accounts receivable are managed and how quickly revenue turns into cash.
Understanding your average collection period helps you spot payment delays, evaluate your credit policies and improve your overall cash flow. Tracked consistently, it also shows trends in customer behavior, so you can act early and keep your collections process efficient and predictable. Keep reading to find out:
- What is Average Collection Period?
- Average Collection Period Formula
- Average Collection Period Example
- Importance of Average Collection Period
- What is a Good Average Collection Period?
- How to Improve Your Average Collection Period
Curious which other AR metrics could help boost your cash flow? Click below to download our free AR metrics spreadsheet and learn how to calculate the metrics that matter most to your business.

What is Average Collection Period?
The average collection period is a financial metric that measures the average number of days it takes for a business to collect payments from customers after a credit sale. It shows how long your accounts receivable remain outstanding before being converted into cash.
This metric plays an important role in understanding your cash flow cycle and evaluating how efficiently your business manages collections. A shorter average collection period generally means customers are paying on time and your collections process is working. A longer period may point to payment delays, lenient credit terms or inefficiencies in your receivables process.
By tracking your average collection period over time, you can spot trends in customer payment behavior and act early to improve how quickly your business gets paid.
Average Collection Period vs AR Turnover vs DSO
The average collection period, accounts receivable turnover and days sales outstanding (DSO) all measure how efficiently a business collects payments, but each presents the information differently.
| Metric | What it measures | Formula | Best used for |
|---|---|---|---|
| Average collection period | Average number of days to collect payment after a credit sale | (Average AR ÷ Net credit sales) × Number of days | Assessing collection efficiency over a full period, such as a year |
| AR turnover | Number of times receivables are collected during a period | Net credit sales ÷ Average AR | Comparing collection efficiency as a ratio in financial analysis |
| DSO | Number of days of sales currently tied up in receivables | (Ending AR ÷ Credit sales) × Number of days | Monthly reporting and tracking trends over time |
The average collection period and AR turnover are two views of the same calculation. Dividing 365 by your AR turnover ratio gives you your average collection period, so as turnover increases, your collection period decreases.
DSO is the metric most finance teams report month to month. The main difference is the receivables figure: the average collection period uses average accounts receivable across the period, while the simple DSO formula uses the ending balance. When receivables are stable, the two give similar results. When AR grows or shrinks sharply during the period, they can differ, and DSO reacts faster to recent changes. Some teams also call this measure days sales in accounts receivable.
Using these metrics together gives you a more complete view of your collections performance: the average collection period and DSO give a time-based measure in days, while the turnover ratio shows efficiency as a ratio.
Average Collection Period Formula
The average collection period calculates how long it takes, on average, for your business to collect payment after a credit sale. It’s expressed in days, which makes it easy to see how quickly cash is coming in.
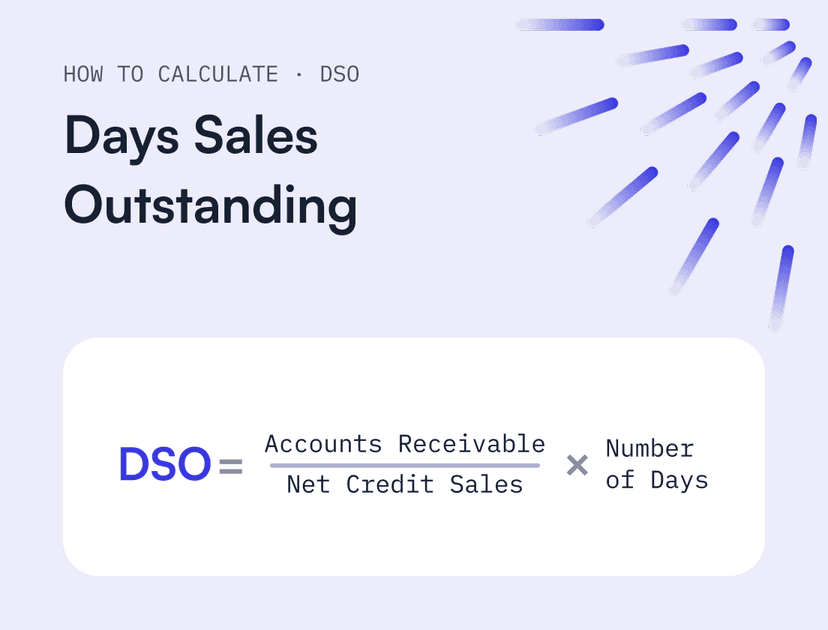
The standard formula is:
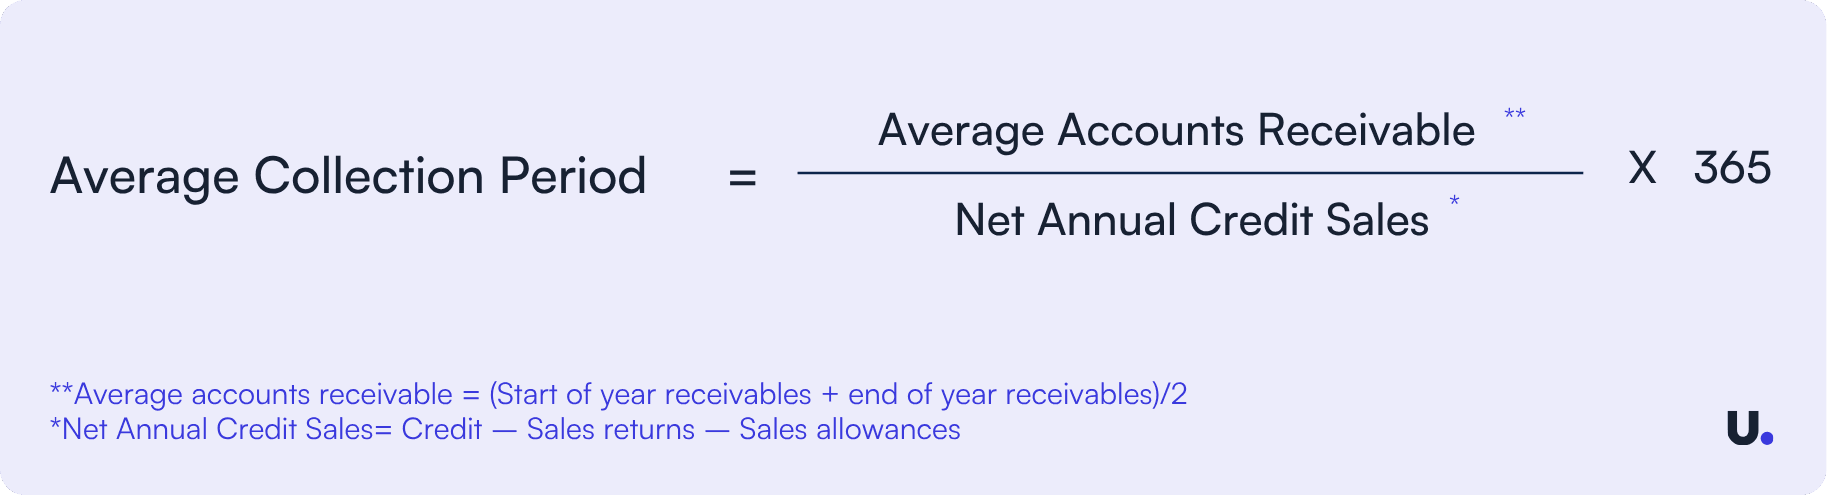
Here it is as text, so you can copy it:
Average Collection Period = (Average Accounts Receivable ÷ Net Credit Sales) × Number of Days
Average accounts receivable is calculated by adding your beginning and ending accounts receivable balances for the period and dividing by two. Net credit sales include all sales made on credit, excluding returns and allowances. For the number of days, use 365 for a year, 90 for a quarter, or the number of days in the month for monthly figures.
This version of the formula gives you a direct view of how your receivables relate to your sales, translated into the number of days it takes to collect payment.
There’s also a simpler way to calculate the average collection period if you already know your AR turnover ratio:
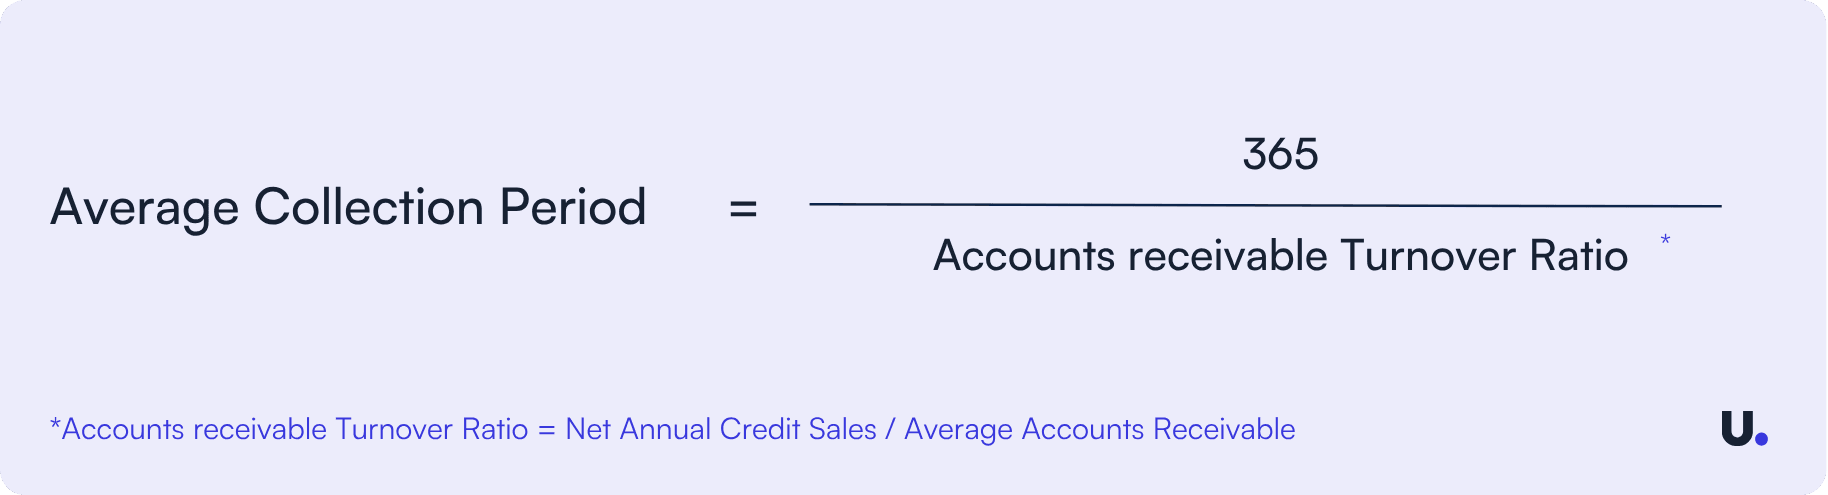
Or, as text:
Average Collection Period = 365 ÷ Accounts Receivable Turnover Ratio
This version converts the turnover ratio into days, which makes your collections performance easier to interpret. A lower number of days means faster collections, while a higher number means it takes longer to get paid.
Want to skip the formulas? Our free spreadsheet works as an average collection period calculator, and works out your AR turnover at the same time. Click on the banner below to download it.

Average Collection Period Example
To see how the average collection period works in practice, let’s walk through a simple example.
Assume your business generated $100,000 in net credit sales over the year. Your accounts receivable balance was $8,000 at the beginning of the year and $12,000 at the end.
First, calculate your average accounts receivable:
($8,000 + $12,000) ÷ 2 = $10,000
Next, apply the formula:
($10,000 ÷ $100,000) × 365 = 36.5 days
Your average collection period is 36.5 days. In other words, it takes your business about 36.5 days on average to collect payment from customers after a credit sale.
You can also reach the same result using the accounts receivable turnover ratio. Your turnover ratio is $100,000 ÷ $10,000 = 10, and dividing 365 by 10 gives you the same 36.5 days.
How to Calculate the Average Collection Period for a Month
The same formula works for a single month. Just use that month’s figures and the number of days in it.
Say your net credit sales for March were $9,000. Your accounts receivable was $11,000 at the start of March and $13,000 at the end:
- Average accounts receivable: ($11,000 + $13,000) ÷ 2 = $12,000
- Average collection period: ($12,000 ÷ $9,000) × 31 = 41.3 days
March’s 41.3 days is higher than the 36.5-day annual figure, which suggests collections slowed down that month. A quick look at your AR aging report will show which customers are behind the change. Tracking the metric monthly like this also gives you a more reliable base for cash flow forecasting, since you can see slowdowns as they happen rather than at year-end.
Looking at the average collection period in this way gives you a clear, time-based view of how quickly your business converts receivables into cash.
Importance of Average Collection Period
The average collection period shows how efficiently your business turns credit sales into cash. It affects your liquidity, your collections performance and your overall financial stability.
- Cash flow management: A shorter collection period means cash comes in sooner, which supports stronger liquidity and reduces reliance on invoice financing to cover gaps.
- Credit policy assessment: The metric shows whether your credit terms are too strict or too lenient. A long collection period can point to relaxed terms or slow follow-up, while a short one reflects tight credit control.
- Customer payment behavior: Tracking it over time highlights consistent delays and high-risk accounts, so you can adjust your financial relationship strategy with each customer.
- Benchmarking: Comparing your collection period with industry averages shows where you stand. Upflow’s research on cash collection benchmarks shows how much collection speed varies across businesses.
- Forecasting and budgeting: A predictable collection period makes cash inflows easier to plan, which improves your cash flow planning. It also gives your cash forecasting a realistic timing assumption for when receivables will turn into cash.
What is a Good Average Collection Period?
A good average collection period is one that’s close to your agreed payment terms and compares well with your industry. In general, shorter is better, since it means you’re collecting efficiently and keeping cash flow strong.
As a rule of thumb, your average collection period should be close to your payment terms. For example, if your terms are net 30, collecting within 30 to 45 days is typically considered healthy. If your collection period sits well above your terms, customers are paying late, whatever your industry.
What counts as good also varies widely by industry. To benchmark performance, many businesses look at median DSO, a closely related metric. Our State of B2B Payments 2024 report shows how it varies across sectors:
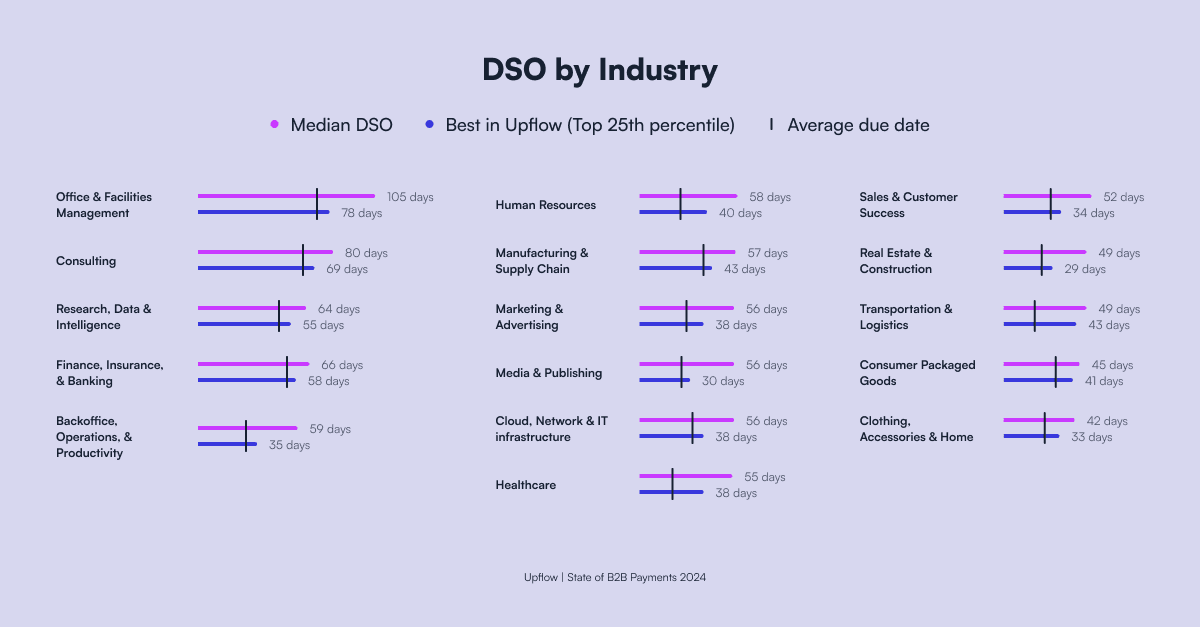
The chart compares the median DSO in each industry with the top 25% of performers on Upflow. Here are the same figures as a table:
| Industry | Median DSO | Best in Upflow (top 25%) |
|---|---|---|
| Office & Facilities Management | 105 days | 78 days |
| Consulting | 80 days | 69 days |
| Finance, Insurance & Banking | 66 days | 58 days |
| Research, Data & Intelligence | 64 days | 55 days |
| Backoffice, Operations & Productivity | 59 days | 35 days |
| Human Resources | 58 days | 40 days |
| Manufacturing & Supply Chain | 57 days | 43 days |
| Marketing & Advertising | 56 days | 38 days |
| Media & Publishing | 56 days | 30 days |
| Cloud, Network & IT Infrastructure | 56 days | 38 days |
| Healthcare | 55 days | 38 days |
| Sales & Customer Success | 52 days | 34 days |
| Real Estate & Construction | 49 days | 29 days |
| Transportation & Logistics | 49 days | 43 days |
| Consumer Packaged Goods | 45 days | 41 days |
| Clothing, Accessories & Home | 42 days | 33 days |
Across all industries, the overall median is 56 days. Traditional service industries like Office & Facilities Management and Consulting tend to have longer collection periods, often because longer payment terms are common in those sectors. Clothing, Accessories & Home businesses collect fastest, thanks to faster inventory cycles and stricter payment enforcement.
These differences come down to how businesses operate. Companies that sell physical goods can enforce payment more easily, for example by holding the next order until outstanding invoices are paid, while service businesses often find it harder to pause what they provide.
Ultimately, a good average collection period is one that aligns with your payment terms and compares favorably with your industry benchmarks.
How to Improve Your Average Collection Period?
When your average collection period starts rising, the cause is usually in your own process rather than with your customers. Start by finding what’s driving the increase, then fix it at the source.
| What's driving it | What to do |
|---|---|
| Invoices sent late or with errors | Invoice as soon as work is delivered, using a standard template |
| Invoices going to the wrong contact | Confirm billing and AP contacts when you onboard each customer |
| No reminders before the due date | Send automated reminders a few days before each invoice is due |
| Disputes left unresolved | Give every dispute an owner and resolve it before it ages |
| Paying is inconvenient | Offer online payment options and a payment link on every invoice |
| Credit terms too generous for risky accounts | Review credit limits and terms based on payment history |
| A few large customers paying late | Escalate early and involve the account owner from sales or customer success |
Once you know where the delays come from, these five strategies will help you reduce your average collection period and get paid faster:
- Implement a consistent invoicing system: Set clear, predictable billing schedules so customers know when and how they’ll be invoiced. That helps them plan their payments and reduces delays.
- Streamline invoices for clarity: Make sure invoices are easy to read and clearly outline each charge. Clear invoices reduce confusion and help customers review and approve payments more quickly.
- Automate payment reminders: Use automated, account-level payment reminders to keep customers informed of outstanding balances, so it’s easier for them to pay on time. You can streamline this process with a financial CRM like Upflow.
- Offer flexible payment options: Provide several payment methods, including an online payment system, so customers can pay as soon as they receive an invoice.
- Incentivize early payments: Offer early payment discounts to encourage customers to settle invoices ahead of the due date.
Applying these strategies consistently will help shorten your average collection period, leading to improved cash flow and stronger financial stability.

Alexandre Antoine
Finance Director at Upflow
Alexandre is the Finance Director at Upflow, where he leads the company’s internal finance and accounting operations. With a background in both strategic finance and financial reporting, Alexandre brings a practical, detail-oriented approach to the complexities of B2B finance.
At Upflow, Alexandre ensures that internal processes from cash management to KPI reporting are optimized for transparency, accuracy, and growth-readiness. He helps build scalable finance systems that support Upflow’s mission to empower other finance teams through better collections and cash flow insights.
Alexandre regularly contributes to Upflow’s blog with in-depth articles on accounting metrics, financial ratios, reporting best practices, and operational benchmarks. His writing provides actionable advice for controllers, FP&A teams, and finance leaders navigating complex financial processes.

Summary

Shared
FAQs
Can’t find what you’re looking for?
Ask AI
The average collection period is the average number of days it takes a business to collect payment from customers after a credit sale. It measures how quickly accounts receivable are converted into cash and reflects the efficiency of your collections process.
The average collection period formula is: Average Collection Period = (Average Accounts Receivable ÷ Net Credit Sales) × Number of Days. You can also calculate it by dividing 365 by your accounts receivable turnover ratio.
To calculate the average collection period, first determine your average accounts receivable by averaging the beginning and ending balances. Then divide that number by your net credit sales and multiply by 365. This gives you the average number of days it takes to collect payment.
Use the same formula with that month’s figures: divide your average accounts receivable for the month by the month’s net credit sales, then multiply by the number of days in the month. For example, $12,000 in average receivables and $9,000 in March credit sales gives ($12,000 ÷ $9,000) × 31 = 41.3 days.
A good average collection period is close to your agreed payment terms and compares well with your industry. On net 30 terms, collecting within 30 to 45 days is typically considered healthy. Across industries, Upflow’s data puts the median DSO, a closely related metric, at 56 days.
Both measure how long it takes to collect payment in days, but they use a different receivables figure. The average collection period uses average accounts receivable across the period, while the simple DSO formula uses the ending balance. When receivables are stable, the two give similar results, while DSO reacts faster to recent changes.
Lower is generally better. A low average collection period means customers pay quickly and cash comes in sooner. A high one can point to late payments, lenient credit terms or gaps in your collections process. The exception is a period that’s far shorter than your terms, which may mean your credit policy is stricter than it needs to be.
Invoice as soon as work is delivered, send clear invoices to the right contact, and automate reminders before and after the due date. Offering online payment options and early payment discounts also helps, as does resolving disputes quickly and reviewing credit terms for accounts that regularly pay late.
You can estimate the average collection period using total sales if credit sales data is not available, but this is less accurate. Including cash sales can make the collection period appear shorter than it actually is, so using net credit sales provides more reliable insights.
Related articles